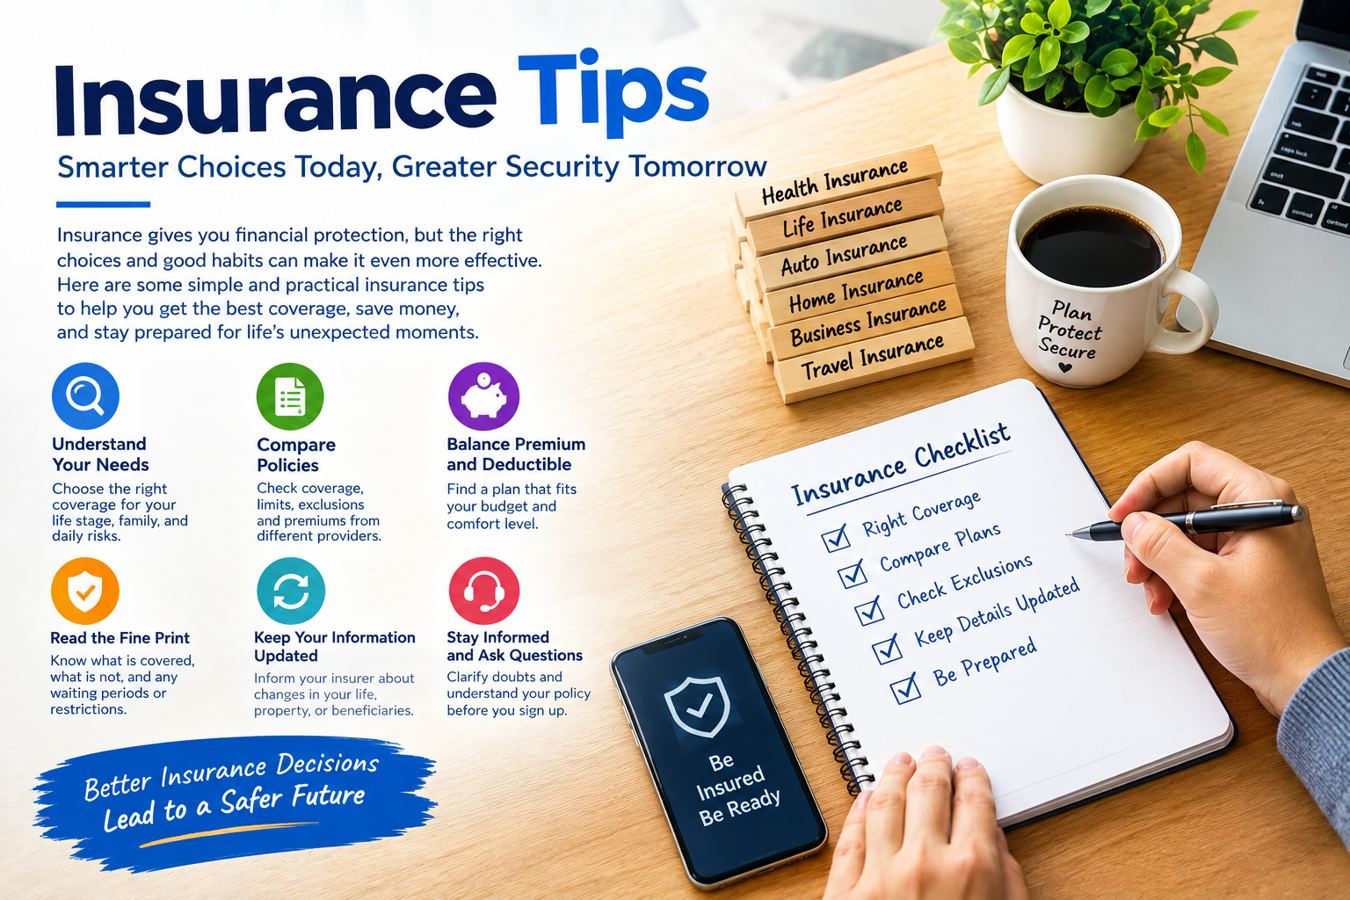
Insurance can be an important part of financial planning, but choosing the right policy is not always simple. With different companies, coverage options, premiums, deductibles, exclusions, and policy conditions, it can be difficult to know what deserves the most attention.
Whether you are looking for health, life, auto, home, business, or travel insurance, taking time to understand your options can help you make more informed decisions. The goal is not simply to find the cheapest policy, but to find coverage that matches your needs and financial situation.
1. Understand What You Actually Need
The first step in choosing insurance is identifying the risks you want to protect against.
For example, a vehicle owner may be concerned about accidents, theft, or liability. A homeowner may want protection for property damage and personal belongings. Someone with dependents may consider life insurance to help protect their family’s financial future.
Before requesting quotes, make a list of the assets, responsibilities, and risks that could create a significant financial problem.
Understanding your needs first can make it easier to compare policies later.
2. Compare More Than One Policy
Insurance prices and coverage can vary between providers. Getting quotes from several insurers can help you understand the available options.
However, do not compare policies based only on the premium.
One policy may cost less but have a higher deductible, lower coverage limits, or more exclusions. Another policy may have a higher premium but offer different benefits.
When comparing policies, try to compare similar levels of coverage so you are making a meaningful comparison.
3. Read the Fine Print
Insurance policies contain important details that advertisements may not explain.
Before purchasing coverage, look carefully at:
Coverage limits
Deductibles
Exclusions
Waiting periods
Claim requirements
Renewal conditions
Additional benefits
Cancellation rules
Understanding these details can help you avoid surprises when you need to make a claim.
If there is something you do not understand, ask the insurance company or an appropriately qualified professional for clarification before purchasing the policy.
4. Don’t Automatically Choose the Cheapest Option
A low premium can be attractive, especially when trying to manage a monthly budget. However, the cheapest policy is not always the most suitable one.
Consider the financial consequences of a major loss and compare them with the protection offered by the policy.
For example, choosing a very high deductible may reduce the premium but could leave you responsible for a larger payment after a covered event.
The right balance depends on your budget and how much financial risk you can reasonably handle.
5. Keep Your Information Updated
Insurance policies are based on information about your circumstances.
If your situation changes, your insurance needs may change as well.
Moving to a new home, buying a different vehicle, getting married, having a child, starting a business, purchasing expensive belongings, or changing how you use a vehicle can all be reasons to review your coverage.
Keeping your insurer informed about important changes can help reduce the possibility of incorrect policy information.
6. Create a Record of Your Important Assets
Keeping records can be extremely useful if you ever need to make a claim.
For home or business insurance, consider maintaining photographs, receipts, serial numbers, and other records for valuable property.
For vehicles, keep important documents such as registration, purchase information, maintenance records, and insurance details organized.
Store digital copies securely so that you can access them if physical documents are lost or damaged.
7. Understand Your Deductible
A deductible is the amount you may need to pay toward a covered claim before the insurer contributes according to the policy.
Before choosing a deductible, consider whether you could comfortably afford it after an unexpected event.
A lower deductible may come with a higher premium, while a higher deductible may reduce the premium. The best option depends on your individual financial circumstances.
Understanding this trade-off can help you avoid choosing a policy based solely on its monthly price.
8. Review Your Insurance Every Year
Insurance should not necessarily be treated as a “set it and forget it” product.
A yearly review can help you determine whether your coverage still matches your current situation.
Check whether your coverage limits are still appropriate, whether your beneficiaries are correct where applicable, and whether you have acquired new assets or responsibilities.
Regular reviews may also reveal opportunities to adjust unnecessary or outdated coverage.
9. Ask Questions Before Signing
Do not hesitate to ask questions before purchasing insurance.
Useful questions include:
What exactly does this policy cover?
What is excluded?
How much is the deductible?
What are the coverage limits?
How do I make a claim?
Are there waiting periods?
Can the premium change?
What happens if I miss a payment?
Are there optional benefits available?
Getting clear answers before purchasing can make it easier to understand what you are paying for.
10. Keep Your Policy Documents Safe
Finally, keep your insurance documents in a secure and accessible location.
Important information can include your policy number, insurer’s contact information, coverage details, renewal date, beneficiary information, and claim instructions.
Having these details available can save time during an emergency.
Final Thoughts
Choosing insurance does not have to be complicated. The most useful approach is to understand your risks, compare policies carefully, read the conditions, and review your coverage when your circumstances change.
Remember that insurance is about managing financial risk, not simply finding the lowest possible price. A policy should provide protection that makes sense for your needs and budget.
By following these simple insurance tips, you can become more confident when comparing coverage and better prepared for unexpected situations.
Note: Insurance products, regulations, prices, exclusions, and coverage requirements vary by country and insurer. This article is for general educational purposes and does not replace an actual insurance policy or professional advice.